One Trade, One Day, Three Continents: Following a Single Bitcoin Order Around the Clock
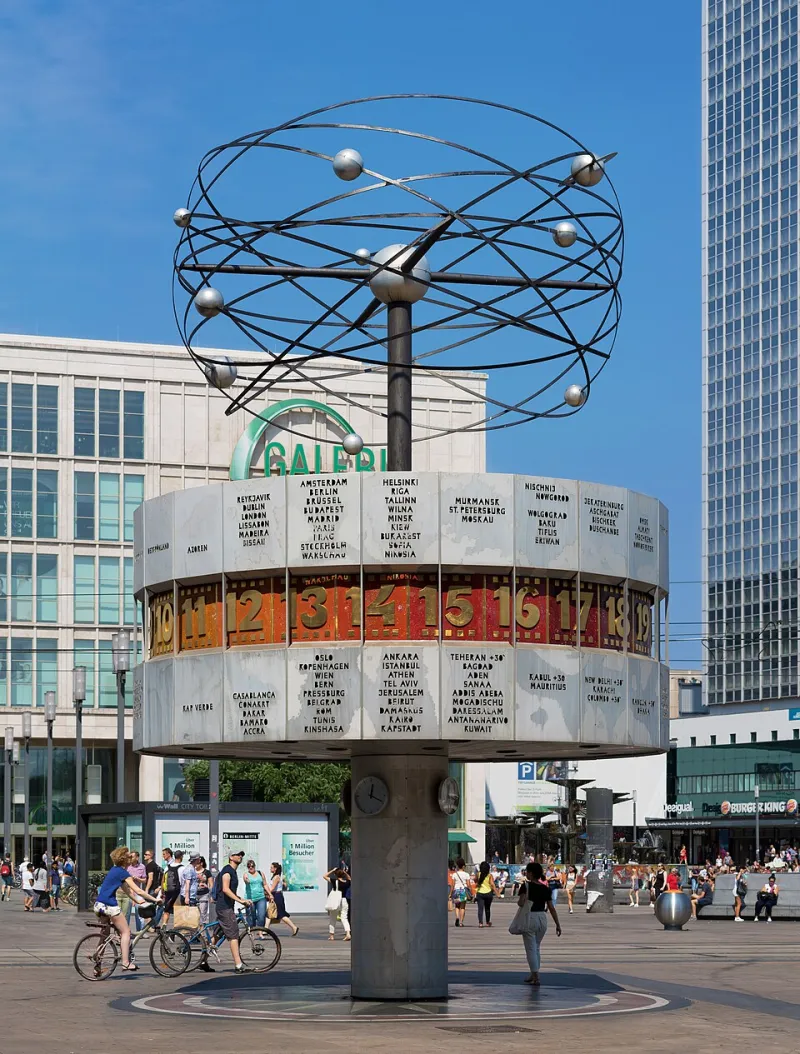
Photo: Christian Wolf (www.c-w-design.de), CC BY-SA 3.0 de, via Wikimedia Commons
Bitcoin trades continuously, but the market it trades in does not stay the same. To understand how much the clock matters, we followed one hypothetical order — a $50,000 market buy of BTC — through a full 24-hour cycle on a major US-regulated exchange, logging the spread, estimated slippage, and order book depth at each session.
The Asian Session: Thin but Steady
At 2:00 a.m. Eastern, the order book was noticeably thinner. The bid-ask spread on our reference pair widened to roughly 2–3 basis points, and visible depth within 0.5% of mid-price dropped by an estimated 40% compared to peak hours. Our simulated order still filled near mid-price — retail-size orders rarely move major pairs — but the cushion was thinner. A larger order would have paid for it.
The European Handoff: Liquidity Builds
Between 3:00 and 5:00 a.m. Eastern, European banks and market makers came online. Depth returned, spreads tightened, and by 8:00 a.m. the book looked healthy again. Notably, this window often produced the day's first directional move — a pattern consistent with the well-documented tendency of BTC to set intraday extremes during the London session.
The US Overlap: Peak Hours
From 9:30 a.m. Eastern, the New York open layered US flow on top of European activity. This was the deepest, tightest market of the day: spreads at or near their daily minimums, slippage on our test order effectively zero. If you're executing a large trade and can choose your window, this is historically the least expensive one.
The Post-Close Fade
After 4:00 p.m. Eastern, liquidity receded in stages. By midnight, the market had returned to Asian-session conditions. The pattern repeated the next day.
What This Means for Ordinary Traders
Three takeaways emerged. First, the asset is the same at every hour; the market is not. Second, limit orders matter far more in thin sessions, because market orders in shallow books pay the spread plus slippage. Third, volatility clustering around session opens — particularly the London and New York handoffs — means stops placed carelessly are more likely to be caught in fast moves.
None of this guarantees better entries. But understanding when the market is deep and when it is hollow is a structural advantage that costs nothing to acquire.